Ivan Johnson is reviewing the investment merits of BioTLab, a fast-growing biotechnology company. BioTLab has developed several drugs, which arc being licensed to major drug companies. BioTLab also has several drugs in phase III trials (phase III trials are the last testing stage before FDA approval). Johnson notes that two drugs recently received approval which should provide BioTLab solid revenue growth and generate predictable cash flow well into the future. Based on the potential for the two drugs, BioTLab's estimated annual cash flow growth rate for the next two years is 25%, and long-term growth is expected to be 12%. Because of BioTLab's attractive investment opportunities, the company does not pay a dividend. BioTLab's current weighted average cost of capital is 15% and its stock is currently trading at $50 per share. Financial information for BioTLab for the most recent 12 months is provided below:
• Net working capita! excluding cash increased from $7,460,000 to $9,985,000;
• Book value increased from $81,250,000 to $101,250,000.
• BioTLab currently has no debt.
• Research facilities and production equipment were purchased for $8,450,000.
• BioTLab held non-operating assets in the amount of $875,000.
• Net income for the 12 months was $20,000,000.
• BioTLab has a marginal tax rate of 40%.
• Noncash charges for depreciation and restructuring for the 12 months were $1,250,000.
BioTLab's management has indicated an interest in establishing a dividend and will fund new drug research by issuing additional debt.
Johnson also reviews a competitor to BioTLab, Groh Group, which has a larger segment operating in a highly cyclical business. The Groh Group has a debt to equity ratio of 1.0 and pays no dividends. In addition, Groh Group plans to issue bonds in the coming year.
Ten years have passed and BioTLab's drug pipeline has generated the expected growth. To support BioTLab's growth, the company levered its balance sheet to a debt-to-equity ratio of 35%. The company recently started paying a dividend equaling 10% of earnings. The company's current return on assets is 10%, with a tax rate of 40% and pretax interest rate of 6%. BioTLab's FCFE equals $20,000,000 and FCFF equals $24,000,000. The company's WACC equals 11% and the required rale of return on equity equals 13%. The FCFE model calculates a value for BioTLab of $1,110,000,000 and the FCFF model calculates a value of $1,308,000,000. Calculate BioTLab's new expected growth rate using the FCFF model.
Answer(s): A
Explanation:
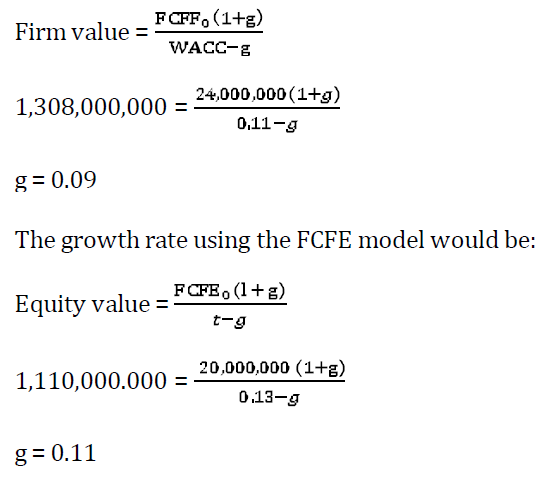
(Study Session 12, LOS 41.k)